
Access all our platforms from a single account.

Asia Market Quick Take – 13 November, 2026
Key points:
- Macro: Trump rules out need for Iran deal
- Equities: Jensen Huang is ousted as Nvidia CEO
- FX: USD strengthens across as yields rise
- Commodities: Oil rises after Trump says no deal needed with Iran
- Fixed income: Treasury selloff deepens as oil jumps and Fed hike premium increases
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- Trump ruled out the need for an Iran deal and told Vance to focus on domestic issues, while Iran demands an end to the naval blockade and sanctions and refuses to give up enriched nuclear material. Still, oil prices are heading for a second weekly decline as Middle East exports recover and Democrats’ midterm win bolsters hopes for a quicker resolution.
- US existing home sales fell 5.5% in October to 3.75 million, the lowest since 2010 and below expectations, amid near-record-high mortgage rates. Inventory rose to 1.59 million (5.1 months of supply), and the median price inched up 0.4% yoy to $416,700.
- UK GDP grew 0.7% qoq in Q3 2026, the fastest pace since early 2024 and in line with expectations, driven mainly by stronger services and investment. Production eked out a small gain, construction fell, and net trade was a slight drag. GDP rose 1.9% yoy, up from 1.4% in Q2.
- US jobless claims rose by 9,000 to 200,000 in the week to November 7, slightly above expectations but still low by historical standards. Continuing claims fell by 13,000 to 1.679 million, near their lowest since March 2023, underscoring a still-robust labor market despite high rates and energy costs.
Equities:
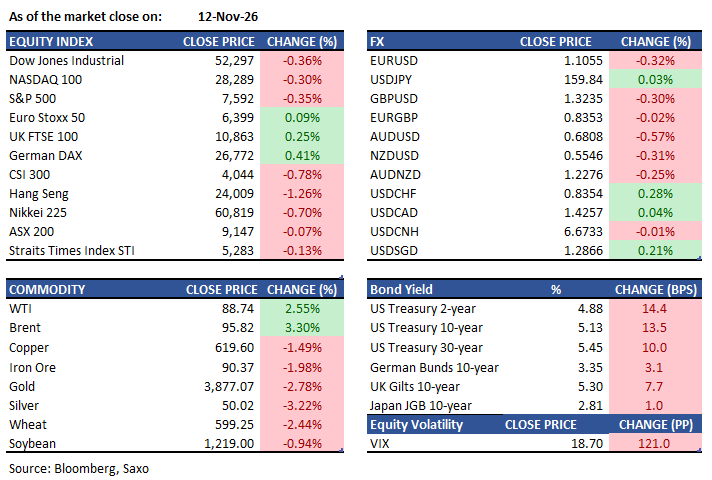
- US — US equities fell on Thursday as Nvidia's leadership crisis and rising oil prices weighed on sentiment. The S&P 500 dropped 0.4% to 7,592, the Nasdaq 100 shed 0.3%, and the Dow fell 189 points. Nvidia sank 4.3% on the CEO ouster, while Broadcom and AMD outperformed. In after-hours trading, Cisco surged after raising its full-year revenue guidance, while Flowers Foods tumbled 13% after cutting its FY sales outlook. Candel Therapeutics fell 42% post-market. US futures are pointing higher this morning, with Nasdaq 100 contracts up 0.6% and S&P 500 futures up 0.4%.
- EU — European stocks eked out a fresh record high on Thursday despite rising oil prices, as rotation out of the AI trade benefited the region. The Stoxx Europe 600 rose 0.1% to 664.01, its fourth consecutive gain. The DAX added 0.4% to 26,772, the FTSE 100 rose 0.3% to 10,863, and the SMI gained 0.6%. Standout movers included Burberry, which surged 8%, and Munich Re, which rose 2.9%. The Euro Stoxx 50 closed up 0.09% at 6,399.
- Asia — Asian stocks are edging higher this morning, shrugging off Thursday's Nvidia-driven headwinds. The MSCI Asia Pacific Index is up 0.3%, led by South Korea. The Kospi and Nikkei are both firmly in the green as Nvidia's partial intraday recovery and buoyant Nasdaq futures lift sentiment. On Thursday, the Hang Seng fell 1.3% to 24,009, dragged by Alibaba (-6.8%) and broader tech weakness on concerns that US authorities are preparing rules to restrict Chinese AI companies' access to advanced semiconductors. The Hang Seng Tech Index dropped 2.4%. SMIC reported Q3 net income of $428m, beating estimates, with revenue up 34% year-on-year. Amicro soared 38% on its Hong Kong debut. Mainland investors were net buyers of HK$5.85bn via Stock Connect on Thursday.
Earnings this week:
- Friday: MUFG; Sumitomo Mitsui Financial; Mizuho Financial; Japan Post Bank; Singtel; Generali
FX:
- USD broadly strength with the Bloomberg Dollar Spot Index rose 0.2% to a fresh 18‑month high, its third straight gain, supported by higher US Treasury yields and a hawkish repricing of Fed expectations after the hot October CPI.
- USDJPY briefly broke above the key 160 level for the first time since September before reversing to close near 159.84. The whipsaw sparked talk of possible official intervention, though neither volumes nor volatility showed extreme stress. The move extends the yen’s third consecutive daily decline as widening US–Japan rate differentials and expectations of more Fed hikes keep pressure on the currency.
- AUDUSD fell 0.57% to 0.6808, making the Aussie the weakest G10 performer, while USDSEK rose 0.54%. Both reflected broad dollar strength and risk‑off sentiment linked to the Nvidia leadership crisis and renewed concerns that higher oil prices could stoke inflation.
Commodities:
- Brent crude surged approximately 3.3% to just over $94/bbl after Trump posted that the US does not need a deal with Iran, reigniting Middle East supply concerns and reversing earlier optimism around a diplomatic resolution.
- Gold tumbled to a one-year low, falling as much as 3.4% to below $3,860/oz on Thursday, as persistent inflation and hawkish Fedspeak drove rate-hike bets higher. Bullion is holding near $3,880/oz this morning, extending its multi-session decline from above $4,100/oz earlier this week.
- Aluminum is in the grip of a significant supply squeeze, with both LME and Shanghai markets in backwardation as declining stockpiles push spot metal to a premium over futures. Buyers face rising prices with little near-term prospect of relief.
Fixed income:
- Treasuries sold off aggressively on Thursday as oil surged and Fed rate-hike premium built further. Short-to-belly yields led the move, with the 2-year rising to around 4.77%, the 5-year up 15bp to 4.97%, and the 7-year up 15bp to 5.04%. The 10-year yield crossed back above 5% for the first time since 22 October. The curve bear-flattened, with 2s10s and 5s30s spreads compressing.
- The US Treasury auctioned $25bn in 30-year bonds at a yield of 5.441%, with a bid-to-cover ratio of 2.36. The auction tailed slightly, keeping long-end yields elevated, with the 30-year closing up 9bp at 5.449%.
- Markets are now pricing approximately 88bp of cumulative Fed tightening by mid-2027, up from 78bp prior to the CPI release, reflecting a meaningful hawkish repricing across the curve. Nomura flagged that the market is clearly contemplating a 50bp hike at the December meeting.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.